The Home Charging Reimbursement File: What to Pay and Prove for Electric Vehicles in 2026/27
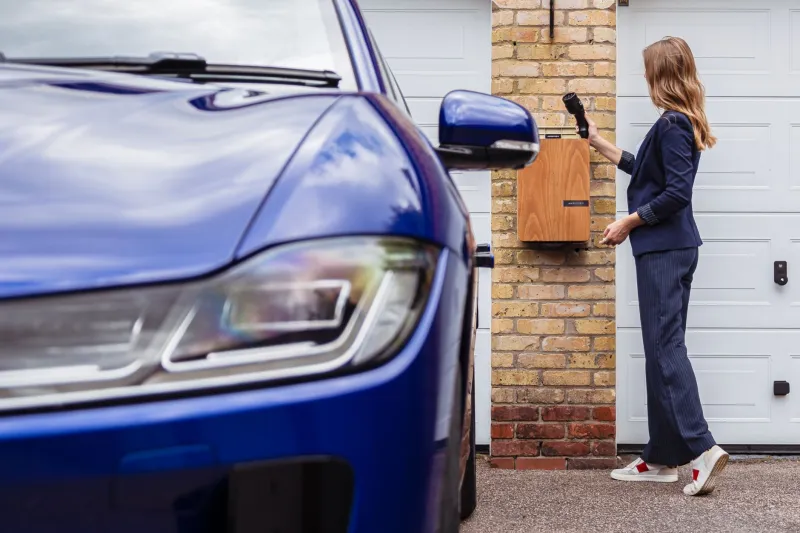
Home charging has become an ordinary running cost for many UK businesses, but its tax treatment is not automatic. A payment towards an employee’s domestic electricity bill can look like a simple expense reimbursement, yet HMRC will test whether it is genuinely business travel, whether the rate is defensible, and whether the paperwork separates business use from private use. The difference between a clean claim and a reportable benefit usually comes down to two things: the rate used and the record kept.
Start with the vehicle and the payer
The first question is not how much the electricity cost. It is who owns the vehicle and who is paying for the power. A company car charged at an employee’s home is treated differently from an employee-owned car used for occasional business journeys. A director’s own electric vehicle raises the same issues as any other employee’s, with the added risk that a company card or director’s loan account can blur the line between company and personal spending.
This article deals with running costs, not the installation of a home charger. Charger installation can have its own benefit-in-kind consequences and should be considered separately.
The advisory electricity rate is a mileage rate, not a subsidy
For electric vehicles used for business travel, HMRC publishes an advisory electricity rate, usually called the AER. It is a pence-per-mile figure, reviewed periodically. The rate in force for the pay period should be used rather than a figure carried forward from an earlier year.
Where an employer reimburses business mileage at or below the published AER, the payment can normally be made without a P11D entry and without tax or National Insurance on the reimbursement. The rate is designed to approximate the cost of electricity for business travel, so it is not necessary to match the employee’s actual domestic tariff mile by mile.
Two limits matter. First, the AER covers business miles only. Private mileage must be excluded. Second, any amount paid above the AER for business miles is generally earnings. It should be taxed and reported through the appropriate payroll or P11D route rather than treated as a tax-free expense. A flat monthly allowance is particularly vulnerable: unless it is clearly calculated by reference to business mileage at or below the AER, HMRC may treat the whole payment as remuneration.
For illustration, if the applicable AER is 7p per mile and an employee records 400 business miles in the month, the defensible reimbursement is £28. A round £50 payment without a mileage calculation leaves £22 of unexplained value.
The record that makes an AER payment stand up
HMRC does not expect an employer to reconstruct a domestic energy bill for every AER claim, but it does expect the business mileage to be evidenced. A practical record should show the date, the employee or director, the vehicle registration, the journey or journeys, the business purpose, the miles travelled, the rate applied and the payment date.
A diary or app-based log is usually sufficient if it is contemporaneous and consistent. The record should distinguish business journeys from commuting and private travel. It should also show that the vehicle is electric and that the rate used is the one published for the relevant period.
Keeping a domestic electricity bill on file is not usually the core evidence for an AER claim, but it can help where the charging pattern is unusual or where the business is paying a significant proportion of a household bill. The stronger control is to pay by reference to miles, not by reference to the size of the energy bill.
Actual cost reimbursement needs a narrower, stronger file
Some businesses prefer to reimburse the exact cost of home charging used for business. That approach is possible, but it demands more evidence. The business should be able to show the electricity tariff, the charging records from a smart charger or app, the business mileage supported by those charges, and a clear apportionment between business and private use.
Actual cost claims should be limited to the business proportion. Paying an employee’s entire domestic electricity bill, or a fixed sum towards it, is unlikely to be defensible without a mileage calculation. Where a home charger serves both a company car and a private car, the apportionment method should be written down and applied consistently.
VAT: usually no reclaim on a reimbursement
An employer cannot normally reclaim VAT on a reimbursement paid to an employee for domestic electricity. The employee is not making a VAT supply to the employer, and the household energy invoice is not addressed to the business. A payment that simply reimburses the employee therefore lacks the input tax evidence needed for a VAT claim.
If the company contracts directly with the energy supplier and the invoice is addressed to the business, VAT treatment may differ, but domestic supply and private use still need to be considered. Domestic electricity is charged at the reduced rate of 5%, and any VAT recovery must be limited to the business proportion. Using a company card to pay a director’s home energy bill without a clear business calculation is a common route to a director’s loan account issue or a taxable benefit.
Sole traders and partners
A sole trader using a personal electric vehicle for business has two broad routes. The simplified mileage rates — 45p for the first 10,000 business miles and 25p thereafter — include the running costs of the vehicle, including electricity. A trader using those rates should not claim home charging separately as well.
Alternatively, a sole trader can claim the actual business proportion of electricity costs. That requires evidence of the cost, the business mileage and a reasonable apportionment. A VAT-registered sole trader may be able to reclaim VAT on the business proportion where a valid invoice is held, but the same principle applies: no double claim and no recovery without evidence.
A practical checklist for 2026/27
- Confirm whether the vehicle is a company car or an employee-owned car.
- Check the advisory electricity rate for the pay period before making the payment.
- Reimburse business miles only, at or below the published rate.
- Keep a contemporaneous mileage log with purpose and vehicle details.
- Avoid round-sum monthly payments unless they are tied to a mileage calculation.
- Treat any excess over the AER as earnings and report it correctly.
- For actual cost claims, retain tariff, charging and apportionment evidence.
- Do not reclaim VAT on an employee reimbursement without valid input tax evidence.
- For sole traders, choose either simplified mileage or actual costs, not both.
The home charging claim is not difficult, but it is evidence-led. A business that pays by business mile, uses the current AER and keeps a clean mileage record will usually stay outside the P11D. A business that pays a comfortable monthly sum and sorts out the paperwork later is storing up a benefit-in-kind question for another day.