Companies House Identity Verification: A Director’s Practical 2026 Timeline

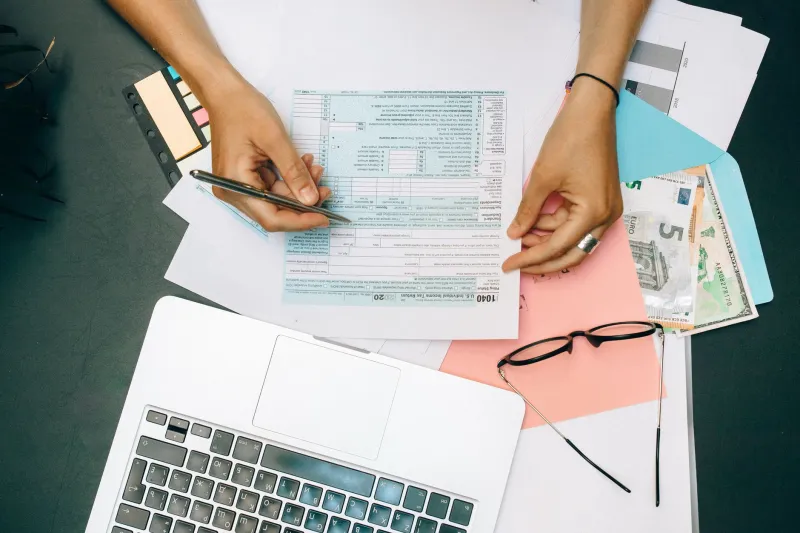
Photo by Photo by Oxana Melis on Unsplash on Unsplash
Companies House identity verification is one of those compliance changes that can sit quietly in the background until a filing is rejected. For directors and people with significant control, it is now part of the ordinary governance of a small company. The sensible approach is to treat verification as a diary item with a clear owner, not as a task to remember at the moment a confirmation statement is due.
Who needs to verify
The requirement applies to directors and people with significant control, often called PSCs. A PSC is generally someone who holds more than 25% of shares or voting rights, or who otherwise exercises significant influence or control. Company owners should check the company's register of PSCs rather than assuming the answer. New directors need to deal with verification before appointment, and existing directors need to act in line with Companies House requirements and their filing cycle.
Why it is linked to the confirmation statement
Identity verification is not a separate tax return. It is a gatekeeping step that connects to Companies House filings, including the confirmation statement. Companies House has been phasing in the requirement, and from 18 November 2025 confirmation statements have been affected for directors and PSCs. If the people named on the register have not completed verification, Companies House may reject a filing or prevent the company from completing the step until the position is corrected. That is why the confirmation statement date should trigger a check of every director and PSC, not just a tick-box review of the registered office.
How verification works in practice
Most people verify through a Companies House account using GOV.UK One Login. The process normally involves confirming identity with a passport or photocard driving licence and completing an online check. An authorised agent can carry out verification in some circumstances, but the director or PSC remains responsible for making sure it is done. Verification is personal and generally reusable across appointments, but the record should still be checked each time a new company or filing is involved.
A practical 2026 timeline
Now: take an inventory
List every director and PSC shown on the public register. Check names, dates of birth and service addresses for discrepancies. Confirm the next confirmation statement due date and identify who will be responsible for the filing. If an adviser handles Companies House filings, agree who is checking verification status and who is chasing the individuals.
Before the next confirmation statement
Ask each director and PSC to verify if they have not already done so. Resolve name mismatches before starting, because a difference between the identity document and the register can slow the process. Keep a simple record of the date, method and result. Do not leave verification until the day before the filing deadline.
When appointing a new director
Make verification part of the appointment pack. A new director should understand that the appointment filing and identity check go together. Check whether the individual has already verified and whether the Companies House record reflects that. If not, build the verification step into the onboarding timetable rather than discovering the gap when the appointment is submitted.
After verification
Update the company's internal records and note the verification date. Store evidence securely and avoid sending copies of identity documents by ordinary email. Set a reminder for the next confirmation statement and for any change of director or PSC. If a director resigns or a PSC's holding changes, update the register and check whether any new individual needs to verify.
What happens if it is ignored
Ignoring verification can lead to rejected filings, which in turn can affect the company's compliance position. Companies House can also use its enforcement powers where requirements are not met, and persistent non-compliance can create wider risks for directors. For a small company, the practical damage is often delay: a bank, lender or counterparty asks for current filings and the company cannot produce them because a confirmation statement has not been accepted.
Common traps for small companies
The first trap is assuming the accountant will handle everything. An adviser can help with the filing, but the individual still needs to complete identity verification. The second is forgetting PSCs because attention is focused on directors. The third is using an old email address or a name that differs from the identity document. The fourth is treating verification as a one-off and failing to check the position when a new director is appointed.
Coordinating with your adviser
Give your adviser a clear list of directors and PSCs, the next confirmation statement date and the current verification status. Use official Companies House channels and avoid sharing Government Gateway or One Login credentials. If an authorised agent is involved, confirm exactly what they will do and what remains with the director. A short written summary of responsibilities is usually enough.
The bottom line
Identity verification is a straightforward task when it is diarised early. The risk comes from treating it as background administration. Check the register, verify the right people, record what has been done and review the position at every confirmation statement. That routine will keep the company's filings moving and reduce the chance of a last-minute rejection.